
Conjoncture Flash October 2026: Treading water
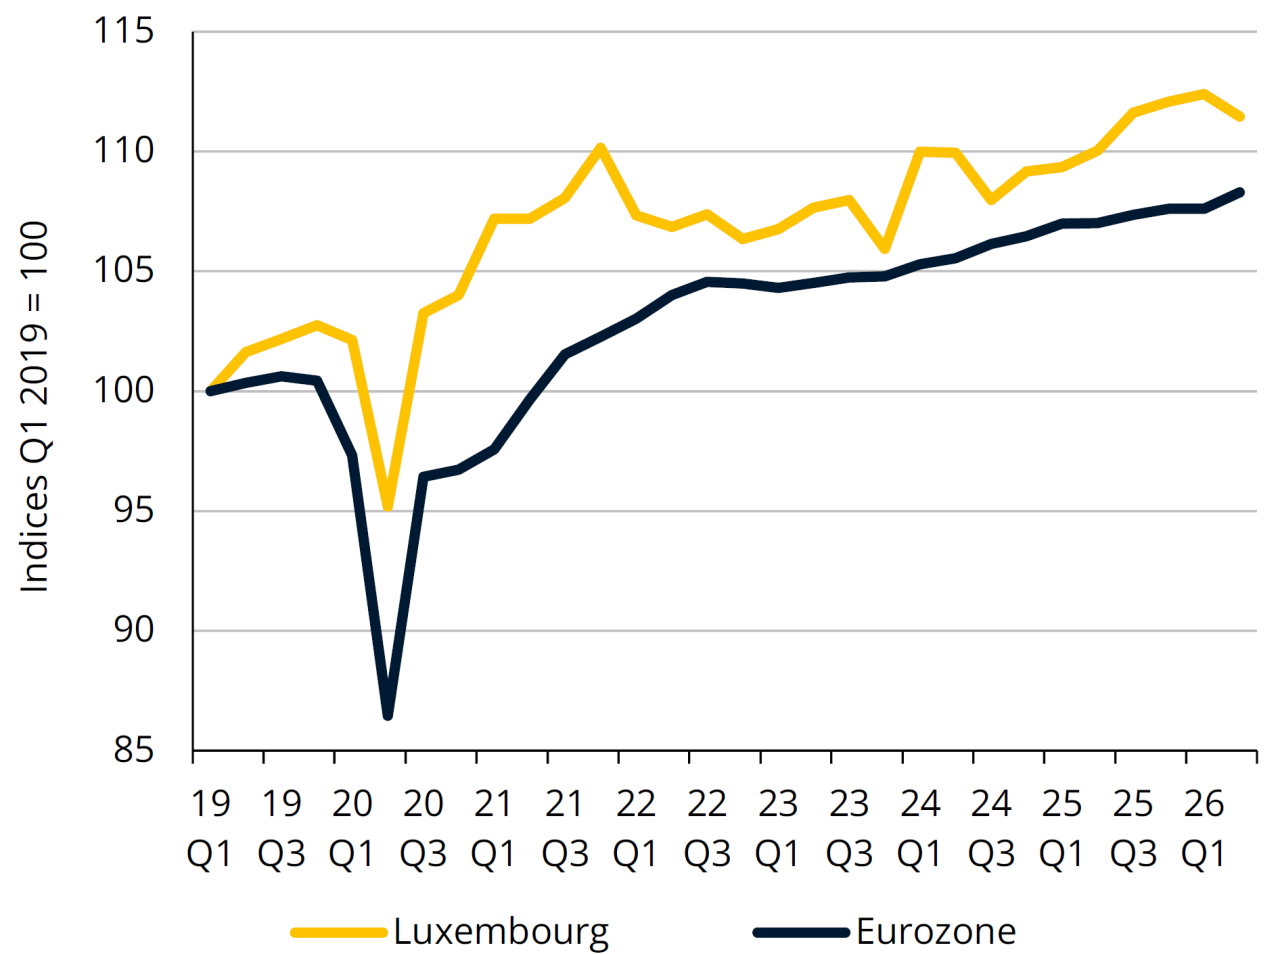
Luxembourg’s GDP declined in the 2nd quarter of 2026. However, this decline comes against a backdrop in which economic activity figures for previous quarters have been significantly revised upward.
On October 7, STATEC published the Gross Domestic Product (GDP) figures for the 2nd quarter of 2026, as well as revised data for the previous quarters and for the years 2024 and 2025 as a whole[1].
Based on these new results, the annual changes in real GDP for 2024 and 2025 have been revised upward: +2.0% for 2024 (up from +0.3% previously) and +1.4% for 2025 (up from +0.6% in the previous quarterly estimates from June 2026). Over these two years, Luxembourg’s growth is therefore higher than that of the euro area (+1.2% in 2024, +1.3% in 2025) – which was not the case in previous estimates – but remains relatively weak compared to the trend observed during the 2010s (+2.5% on average per year).
According to a preliminary estimate, real GDP contracted by 0.9% quarter-on-quarter in the 2nd quarter of 2026. This decline is primarily due to lower investment spending (gross fixed capital formation), a deterioration in the balance of trade in goods and services (which had risen sharply in the two previous quarters), and, to a lesser extent, a decline in household consumption.
Despite this sharp decline in the 2nd quarter of 2026, it should be noted that the growth trajectory of GDP (as well as that for value added) has been significantly revised upward for the three preceding quarters. The growth carry-over for 2026 – that is, the annual growth rate calculated assuming that GDP stabilizes at its second-quarter level for the remainder of the year – thus stands at 0.8%, a result comparable to that obtained following the previous release of the quarterly accounts. Based on these figures, STATEC’s growth forecast of 1.2% for 2026 as a whole (see Note de conjoncture 1-26[2]) remains achievable.
Value added in volume terms also declined by 0.9% quarter-on-quarter in the 2nd quarter. This decline stems primarily from decreases recorded in the financial and insurance sector (whose results remain robust in value terms, driven by valuation effects; see below), manufacturing, and business services. Conversely, information and communication services made a positive contribution (for the fourth consecutive quarter) to the change in value added in volume, as did predominantly non-market activities (public administration, education, and health care).
Regarding revisions to the annual data for 2024 and 2025, the most significant upward revisions for value added in volume relate to business services and manufacturing. By contrast, the performance of information and communication services and of the “Trade, transportation, accommodation, and food services” sector were revised downward.
GDP in volume, Luxembourg vs. eurozone
Sources: Eurostat, STATEC (seasonally adjusted data)
What’s next?
After a sharp decline in the 2nd quarter following the outbreak of the conflict in Iran, business surveys generally showed an improvement in business and household sentiment in the 3rd quarter, both across the eurozone as a whole and in Luxembourg[3] .
For the final quarter of the year, the outlook appears far less encouraging, particularly due to the geopolitical situation in the Middle East. Oil prices continue their upward trend, which began in July (surpassing the USD 115 mark again in late October), reigniting inflationary pressures and prompting tighter monetary policies. These developments are expected to affect household demand and business investment, which have already been severely impacted by the consequences of the 2022–2023 energy crisis. Furthermore, particularly in response to rising energy prices (and their rapid impact on purchasing power) as well as difficulties in accessing housing, social protests are spreading across several European countries (France, Italy, Portugal, Greece, Belgium, and Spain).
[1] The complete annual national accounts for 2024 have been revised, and a first estimation of the complete annual accounts for 2025 has been established. These revisions incorporate, in particular, new information that is available only on an annual basis, new data sources, and methodological adjustments.
[2] https://statistiques.public.lu/dam-assets/catalogue-publications/note-conjoncture/2026/ndc-1-26-web.pdf (Pdf)
[3] There are two exceptions to this finding: a decline in business confidence among construction firms in the eurozone and among retail firms in Luxembourg.
International
Evolution of 10-year bond yields since february 27, 2026

Source: Macrobond
Rising sovereign yields in G7 economies
Since the outbreak of war in Iran on February 28, 2026, sovereign bond markets have tightened considerably. The 10-year sovereign yield has risen particularly sharply in France (+180 basis points), followed by Italy (+133 bp), the United States (+116 bp), the United Kingdom (+108 bp), Japan and Germany (77 bp each), and Canada (+74 bp). French and U.S. yields exceeded 5% in October, a record high since 2002, while Japan’s yield reached its highest level in 30 years.
This synchronized rise in G7 sovereign yields is driven by a combination of factors: mounting inflationary pressures, restrictive monetary policies, increased global demand for financing, and an unstable international environment. Furthermore, widening deficits and rising public debt are prompting investors to demand a higher risk premium. Rising interest rates increase the cost of debt, which may, in the long run, raise questions about the sustainability of public debt in the most indebted economies.
Inflation 1/2
Inflation forecasts for the eurozone

Source: Oxford Economics
Inflation forecasts revised upward
Following the sharp rise in Brent crude oil prices this summer, Oxford Economics (OE) – whose projections serve as the basis for STATEC’s forecasts – has significantly revised upward its inflation outlook for the euro area for the end of 2026 and for 2027.
Last July, OE’s baseline scenario still assumed that the price of Brent would fall to USD 74 per barrel in the 3rd quarter and to USD 72 in the 4th. Now, Brent is projected to stand at around USD 96 in Q3 and to even reach USD 112 in Q4. In 2027, the decline is expected to be more gradual, with the price per barrel falling from USD 105 in the 1st quarter to USD 88 in the 4th quarter. With these new assumptions, the outlook for energy inflation in the euro area has been revised sharply upward: +4.7 percentage points in 2026, reaching 10.2%, and +5.2 percentage points in 2027, settling at 2.4%. Headline inflation, meanwhile, has been raised by 0.4 percentage points in 2026 (to 3.0%) and by 0.7 percentage points in 2027 (to 2.7%).
As for food inflation, the uptick anticipated in July – which was expected to push price increases to around 2% by year-end – has not materialized at this stage (+1.2% in Q3). Instead, the combination of rising energy costs and extreme weather events is expected to reignite inflationary pressures on food prices in 2027 (+2.9%, compared with 2.4% in the July projections). STATEC will release its next inflation forecasts for Luxembourg on November 4, 2026.
Financial sector
Gross value added of the financial sector in Luxembourg

Source: STATEC (seasonally adjusted data)
Valuations rise, volumes decline
In the 2nd quarter, the financial sector’s gross value added (GVA) at current prices rose by 2.9% quarter-over-quarter (+12.8% year-over-year). Life insurance companies saw premiums for guaranteed-return products increase by 11% (+23% year-over-year), while unit-linked products declined slightly (-0.9% quarter-over-quarter, +3% year-over-year). Banks’ earnings rose by 8% quarter-over-quarter (+6.5% year-over-year), driven by a recovery in net interest margins and higher net commission income from custodian banks. The latter benefited from strong growth in the assets of collective investment schemes (+8% quarter-over-quarter, +16% year-over-year), driven by asset valuations.
However, these valuations are neutralized when converting GVA at current prices (in value) to GVA at constant prices (in volume), the latter being necessary for calculating real GDP. The indicators used to deflate GVA – that is, to remove the effects of prices and the valuation of financial services – are primarily interest rates, the valuation of investment fund assets, and consumer prices for financial services. These implicit prices rose by 4.5% quarter-over-quarter (+14% year-over-year), weighing on the growth of GVA in volume terms (-1.5%, -0.8% year-over-year).
Labor market
Job vacancy rate

Sources: ADEM, STATEC (seasonally adjusted data)
More job openings in healthcare, construction, and retail
The job vacancy rate – which measures the ratio of open positions (reported to ADEM) to the total number of open and filled positions – fell by half between the end of 2022 (when it reached a record high of 2.7% during the post-COVID recovery) and the beginning of 2025. Since then, it has generally stabilized. However, this apparent stability masks contrasting trends across different sectors.
Business services have seen the sharpest decline. After reaching nearly 7% in the fall of 2022, the vacancy rate gradually fell to 2% in the 3rd quarter of 2026 (-340 job openings year-over-year). In manufacturing and transportation, the number of job openings also declined (-140 and -70 positions, respectively, year-over-year). In contrast, the vacancy rate reached record levels in health care and social services (+230 positions year-over-year, or +1/3), even though workforce growth in this sector is among the most dynamic (+4.0% year-over-year in Q3, according to preliminary data). The construction sector also has 200 more job openings than a year ago, reflecting improved hiring prospects of companies in the sector, and the retail sector has just over 100 more.
Wages
Compensation per employee

Source: STATEC – National Accounts
Marked slowdown in wages in the 2nd quarter
Compensation per employee slowed significantly in the 2nd quarter in Luxembourg, rising by only 2.1% year-over-year, down from 3.7% in the previous quarter. This is partly due to a smaller contribution from the wage indexation mechanism (+1.7% in Q2 versus 2.5% in Q1). With the indexation in June 2026, this contribution will rise again in the 3rd quarter (to 2.5%). On the other hand, a sharp decline in bonuses and gratuities (approximately -5% year-over-year per employee) slowed the growth of labor costs. This decline is particularly pronounced in the health and social services sector due to a base effect (exceptionally high bonuses in the 2nd quarter of 2025), which explains the sharp drop in the contribution of non-market activities to the growth of overall compensation per employee. A significant decline in bonuses and gratuities is also observed in the information and communications sector.
Furthermore, the increase in employer contributions (linked to the pension reform) has been making a steady and positive contribution to compensation per employee growth since the beginning of 2026. Autonomous wage increases (increases excluding indexation and the factors mentioned above) also contribute to this growth, but to a more limited extent than in 2025.
Inflation 2/2
Price trends for memory and related computer hardware

Sources: Eurostat, Stanford University
*Consumer price indices for these products in the eurozone.
AI is putting pressure on memory prices
Since the fall of 2025, memory prices have risen sharply due to the artificial intelligence boom. Demand from data centers dedicated to AI – which are heavy consumers of DRAM memory – has absorbed a growing share of global production capacity, reducing the volumes available for other uses. This reallocation has led to a sharp rise in memory prices and, in turn, in the prices of storage media and certain computer equipment.
In the eurozone, prices for blank storage media, such as USB flash drives and external hard drives, rose by 52% year-over-year in September 2026, while prices for computers, laptops, and tablets rose by 12%, and prices for mobile phone equipment rose by 1.5%. For the latter category, however, the price increase is still a recent development. The trends observed in Luxembourg are broadly similar.
This upward trend in 2026 contrasts with what has been observed over the past 25 years. Since the early 2000s, these prices had in fact followed a structurally downward trend, linked to productivity gains and technological progress.
Energy
Spot prices for gas and electricity

Source: Macrobond
The war in Iran is affecting other energy prices
The conflict in the Middle East initially triggered a sharp rise in oil and petroleum product prices. However, its repercussions are also beginning to be felt in other energy markets. Since the start of the conflict, wholesale gas prices have begun to rise, as the Middle East accounts for nearly 20% of global natural gas production. As was the case during the 2022 energy crisis, rising gas prices are also putting upward pressure on electricity prices, due to the way the European electricity market operates. Gas and electricity prices, however, remain well below the levels seen in 2022.
In Luxembourg, this increase is not yet reflected in consumer prices for households. This is because energy suppliers cover a significant portion of their needs by purchasing energy in advance. However, if the rise in wholesale prices continues, it could gradually be passed on to the gas and electricity prices paid by households. Some businesses may already be feeling the effects, as changes in market prices are generally passed on more quickly to business customers than to residential customers.
Dashboard

Source: STATEC. QNA – Quarterly National Accounts. 1Estimates based on half-yearly data
Indicators


Last update